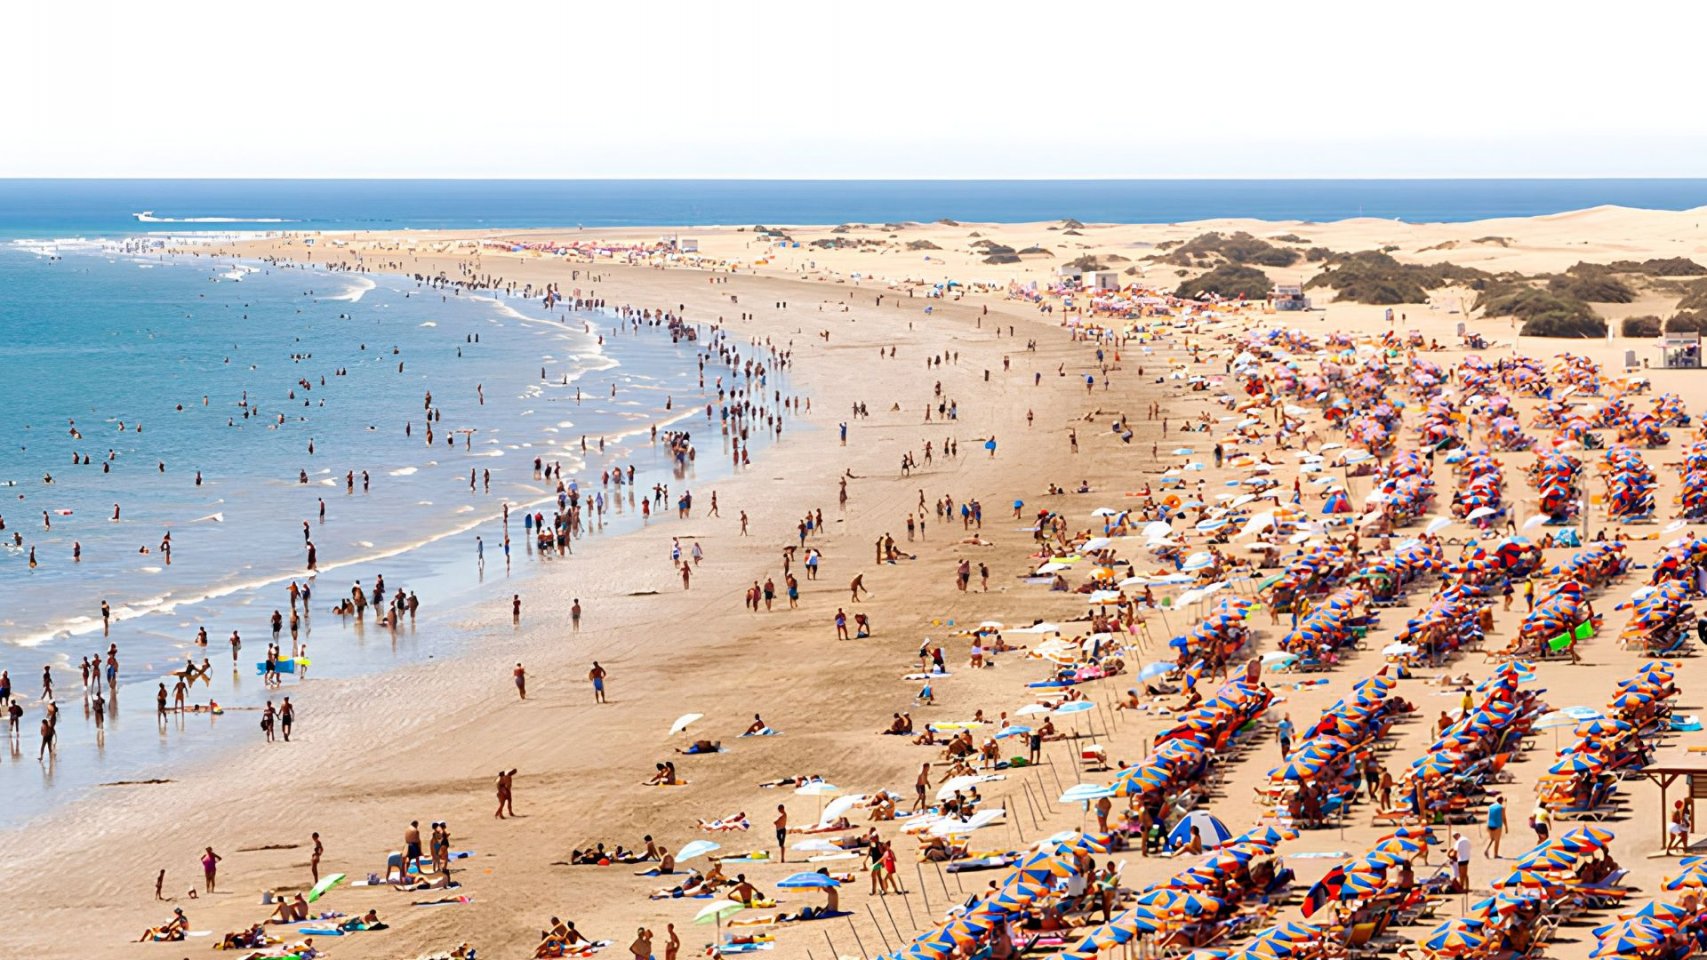
It would be interesting to see how much of the AIEM tax actually reaches southern Gran Canaria. If Las Palmas receives millions of euros, southern Gran Canaria should receive only 200 euros. The renovation of accommodation facilities in southern Gran Canaria faces a structural challenge that goes beyond financing and urban planning: the cost of materials. An analysis of data from the Import and Delivery Tax (AIEM) reveals an intricate network of levies that significantly increases the cost of modernizing the archipelago's tourism infrastructure.
Far from being neutral, the tax applies differential rates that directly impact the bottom line of any comprehensive renovation project in established tourist areas like Maspalomas, Playa del Inglés, or Mogán. For example, rigid ethylene polymer pipes are taxed at 15% if used for general construction, but at 5% if intended for agriculture with embedded drip irrigation systems. This disparity suggests a prioritization of economic sectors that indirectly penalizes tourism in its efforts to modernize.
This tax reality affects not only large hotel chains but also small local property owners trying to modernize their properties. A prime example is that of a civil servant in Las Palmas de Gran Canaria who, after years of saving, decides to renovate his apartment in the Maspalomas tourist area to use as a holiday rental or for his own future enjoyment. Upon starting the renovations, he discovers that the initial budget has skyrocketed due to the AIEM tax, an additional cost he hadn't fully anticipated.
The construction sector, essential for the conversion of hotels and apartments, faces considerable tax pressure. Basic materials needed to build or renovate a tourist establishment are subject to tax rates ranging from 5% to 15%. For example, plastic doors and windows are taxed at a rate of 5%.
This same tax applies to structural metal elements. However, the tax rate increases for finished products such as furniture and equipment. Metal shelving is taxed at 15%, while bed frames and mattresses are taxed at 5%. These differences create a cumulative effect that increases the final budget for renovation projects, hindering the economic viability of many upgrading projects.
In the case of the civil servant in Las Palmas, the AIEM tax increases the cost of everything from the concrete structure and interior furnishings of the room to the electrical and plumbing installations. For example, the purchase of imported tiles, toilets, or shower screens carries a tax that is passed directly on to the end consumer.
The same applies to the purchase of appliances such as a refrigerator or washing machine, or decorative items. This additional cost, which can represent an increase of several thousand euros in an average renovation, drastically reduces the profit margin or investment capacity of the owner, jeopardizing the viability of many initiatives to improve the quality of tourist accommodation.
The paradox of the AIEM lies in its dual purpose: to protect local industry and to tax final consumption to finance public coffers. However, in an island market with limited local production capacity for certain goods, the tax acts as an unavoidable additional cost for investors. The tourism sector, the island's main economic engine, thus becomes the primary taxpayer of a tax that levies its own renovation inputs.
This situation is particularly critical for companies in southern Gran Canaria seeking to improve the quality of their facilities to compete with other international destinations, as the AIEM tax increases the cost of everything from the concrete structure and interior furnishings of the room to the electrical and plumbing installations.
Furthermore, the policy of exemptions and reduced rates creates additional distortions. While some products necessary for agriculture benefit from reduced rates (5%), construction materials essential for the tourism sector continue to be taxed at high rates. In a context where the renovation of accommodation facilities is a strategic imperative to maintain the competitiveness of Gran Canaria as a tourist destination, the AIEM structure stands as a significant tax barrier that increases the cost and complicates the necessary redevelopment of the south of the island, affecting all stakeholders, from large investment groups to small property owners like the civil servant in Las Palmas.